Wednesday, November 11, 2026
A flood zone designation reads like an insurance matter. For anyone holding or acquiring development land on Oahu, it is a site planning matter first, and the insurance follows from it.
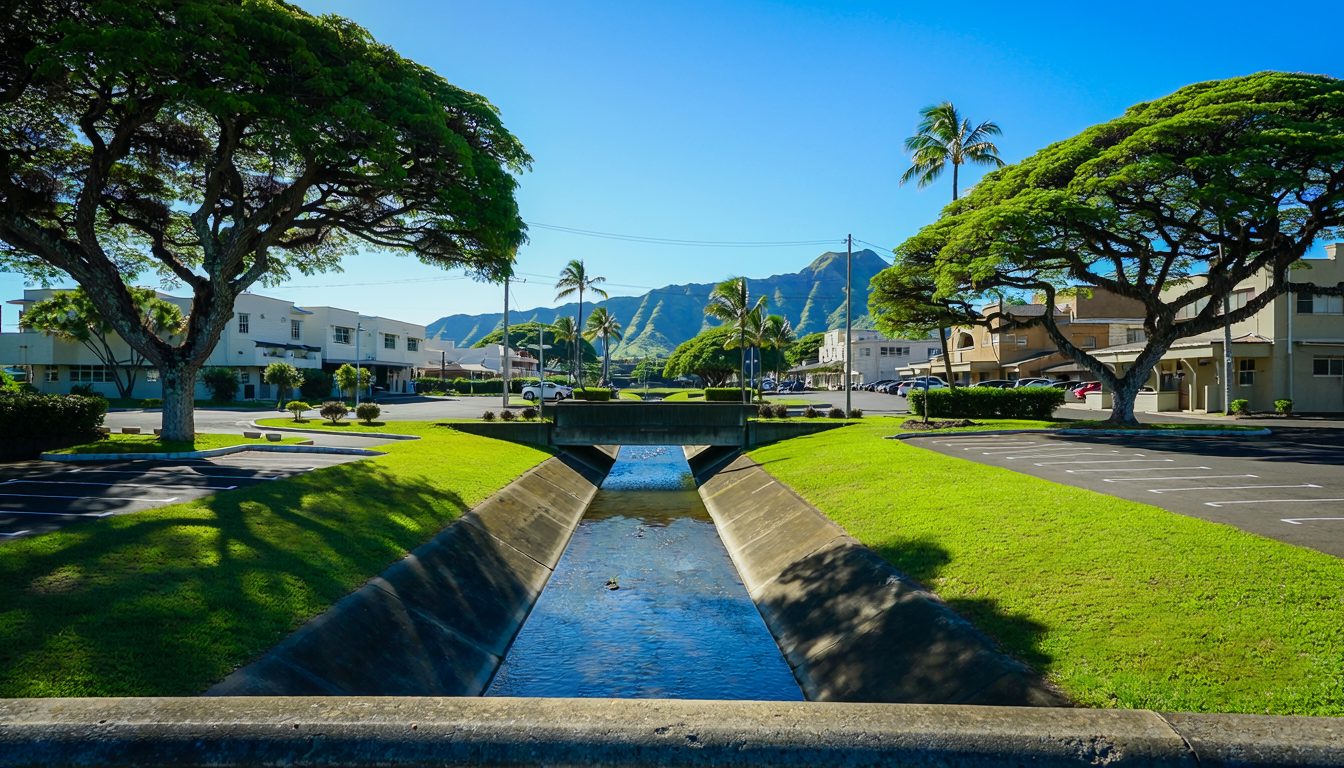
FEMA’s updated Flood Insurance Rate Maps for the City and County of Honolulu took effect on June 10, 2026, the first island-wide remapping in more than a decade. The City reports roughly 3,700 parcels moved into Special Flood Hazard Areas for the first time, with zones redrawn along close to 100 miles of Oahu streams.
What that has changed for owners and developers is not primarily what a property costs to insure. It is what can be built on it.
The immediate effect of a new designation is on elevation and foundation requirements, and those feed straight back into the site plan.
“Their design assumptions changed overnight,” says Mike Perkins of The Bratton Team at Colliers International Hawaii, describing owners who found their parcels newly mapped.
The scale of that effect can be substantial. Perkins points to one commercial development where the new mapping eliminated roughly sixty percent of the buildable area as the site had been planned. The buildable area was ultimately recoverable through site improvements, raising portions of the parcel, but the solution carried redesign work and infrastructure cost that had not been in the original budget.
That is the pattern worth understanding. A zone change rarely makes a site undevelopable. It changes what developing it requires, and the cost of finding that out late is considerably higher than the cost of checking early.
Chapter 21A of the Revised Ordinances of Honolulu now applies to all properties within a Special Flood Hazard Area, and its central requirement is straightforward: new construction and substantial improvements must have the lowest floor at or above the required flood elevation.
How that gets achieved differs by use. Residential buildings must be elevated. Commercial buildings can often be flood-proofed instead, which gives a commercial developer a route that a residential one does not have. Coastal high hazard zones carry stricter rules again on foundations and enclosures.
The design consequences run further than the floor level. Raising a building affects ground floor area, parking layout, and access, and on smaller coastal lots those constraints can reduce what is realistically buildable below what the zoning permits on paper. Perkins’s framing is that a flood designation shapes the building more than it shapes the use.
For a developer, the practical implication is that zoning density and achievable density are now two different numbers on any site inside an SFHA, and only one of them is in the zoning code.
The market response to a new designation follows a recognizable pattern.
There is an immediate discount, driven largely by uncertainty: owners and buyers know the designation has changed and do not yet know what it costs. As the actual insurance and compliance costs become clear, the market absorbs them, and pricing settles around the known number rather than the feared one.
That creates a window. A parcel newly mapped and priced on uncertainty is being valued less precisely than one where the engineering has been done and the costs are established. For a buyer willing to commission the work, the gap between the two is where the opportunity sits.
The item Perkins flags most directly is that buyers are not yet checking the new maps consistently.
Asked whether flood designation has entered standard due diligence, his answer is that it has not, and that it is catching people out. Many market participants are still unaware the maps changed.
For anyone acquiring on Oahu, three checks now belong in the process. Confirm the current flood zone designation against the updated maps rather than against prior knowledge of the parcel. Obtain an elevation certificate, which establishes where the structure or grade sits relative to base flood elevation and drives both insurance pricing and renovation requirements. And price Chapter 21A compliance into the development budget, where costs vary widely enough that Perkins describes them as sometimes sufficient to cancel a project outright.
Assets where that work has already been done carry a premium for the same reason a permitted site does. The uncertainty has been removed. Current Hawaii commercial inventory reflects a market where that distinction is becoming more visible.
Two routes exist for owners who believe the mapping is wrong for their parcel, and they differ sharply in cost.
A Letter of Map Amendment is relatively inexpensive and quick. It makes sense where an elevation certificate shows the structure or its grade sits above base flood elevation, which indicates the map was drawn too broadly for that site. A successful LOMA can remove the mandatory insurance requirement entirely.
A Letter of Map Revision is a different undertaking, revising the map itself with new engineering data. It is costly and slow, and Perkins’s assessment is that it generally makes sense only for larger sites, or for groups of owners acting together where substantial aggregate value is at stake.
The distinction matters because a number of affected properties sit well away from any visible water source and are mapped on modeled stream behavior rather than observed flooding. For those owners, the elevation certificate is the document that determines which route, if either, is worth pursuing.
For developers, the broader conclusion is that Oahu’s buildable land has been quietly re-sorted. The sites that pencil today are not identical to the sites that penciled in May, and knowing which is which has become part of the underwriting. Recently closed Hawaii transactions show a market that is still working through the implications.
About the Expert: Mike Perkins (S) is Associate Vice President with The Bratton Team at Colliers International Hawaii in Honolulu, specializing in development and income-producing commercial assets.
The Bratton Team is a Hawaii commercial real estate and investment sales group, exclusively contracted to Colliers International HI, LLC. Led by Mark D. Bratton (R) CCIM and Mike Perkins (S), the team has advised buyers and sellers across all Hawaii asset classes for 40 years.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.
Disclosure: Individuals or companies mentioned may have a commercial relationship with KeyCrew.


Comments
No comments on this item Please log in to comment by clicking here